
Key Takeaways
- —Most new homes in North Cyprus are bought on a developer payment plan rather than with a bank mortgage.
- —The plan on the Belmaris and West Park pages: a £2,000 deposit, 35% down on signing and the remaining 65% over 36 equal monthly instalments (November 2026).
- —Instalments are in sterling, so a buyer who earns in another currency carries the exchange rate risk every month.
- —Under the decree-law in force, where there is no mortgage in the seller's favour, the period for transferring the title starts once the full price has been paid.
- —Halkbank's TRNC home loan is open to TRNC and Turkish citizens resident in the TRNC; foreign buyers should ask banks about their options directly.
Most people buying a new apartment in North Cyprus never speak to a bank. They pay the developer directly, on a schedule written into the contract. This guide explains how such a plan is put together, what to check from the down payment to the last instalment, and at what point the title deed moves into your name. We sell our own projects on instalments too, so the examples come from there; every figure is public on the project pages.
How does a developer payment plan work?
The idea is simple: the seller gives you credit instead of a bank. Off-plan sales usually have three parts. First a reservation payment that takes the unit off the market, then a down payment due when the sales contract is signed, and finally monthly or stage-based instalments for the balance. Down payments vary by project; around a third of the price is a common starting point in this market.
Resale homes are different. The seller is usually a private owner who does not want to wait years for the money, so the price is paid in one go or over a short plan of a few months.
Linked to the calendar or to construction?
There are two models. With a calendar plan you pay the same amount every month, and the instalments keep coming even if the build slows down. With a stage plan, payments fall due as the foundations, frame, roof and finishing works are completed. The second protects the buyer better but is harder to budget for, because what you pay in a given month depends on progress on site. If you are negotiating a stage plan, knowing how a contractor moves a site from one stage to the next helps you tie each payment to a specific piece of work in the contract.
A worked example: down payment and monthly instalments
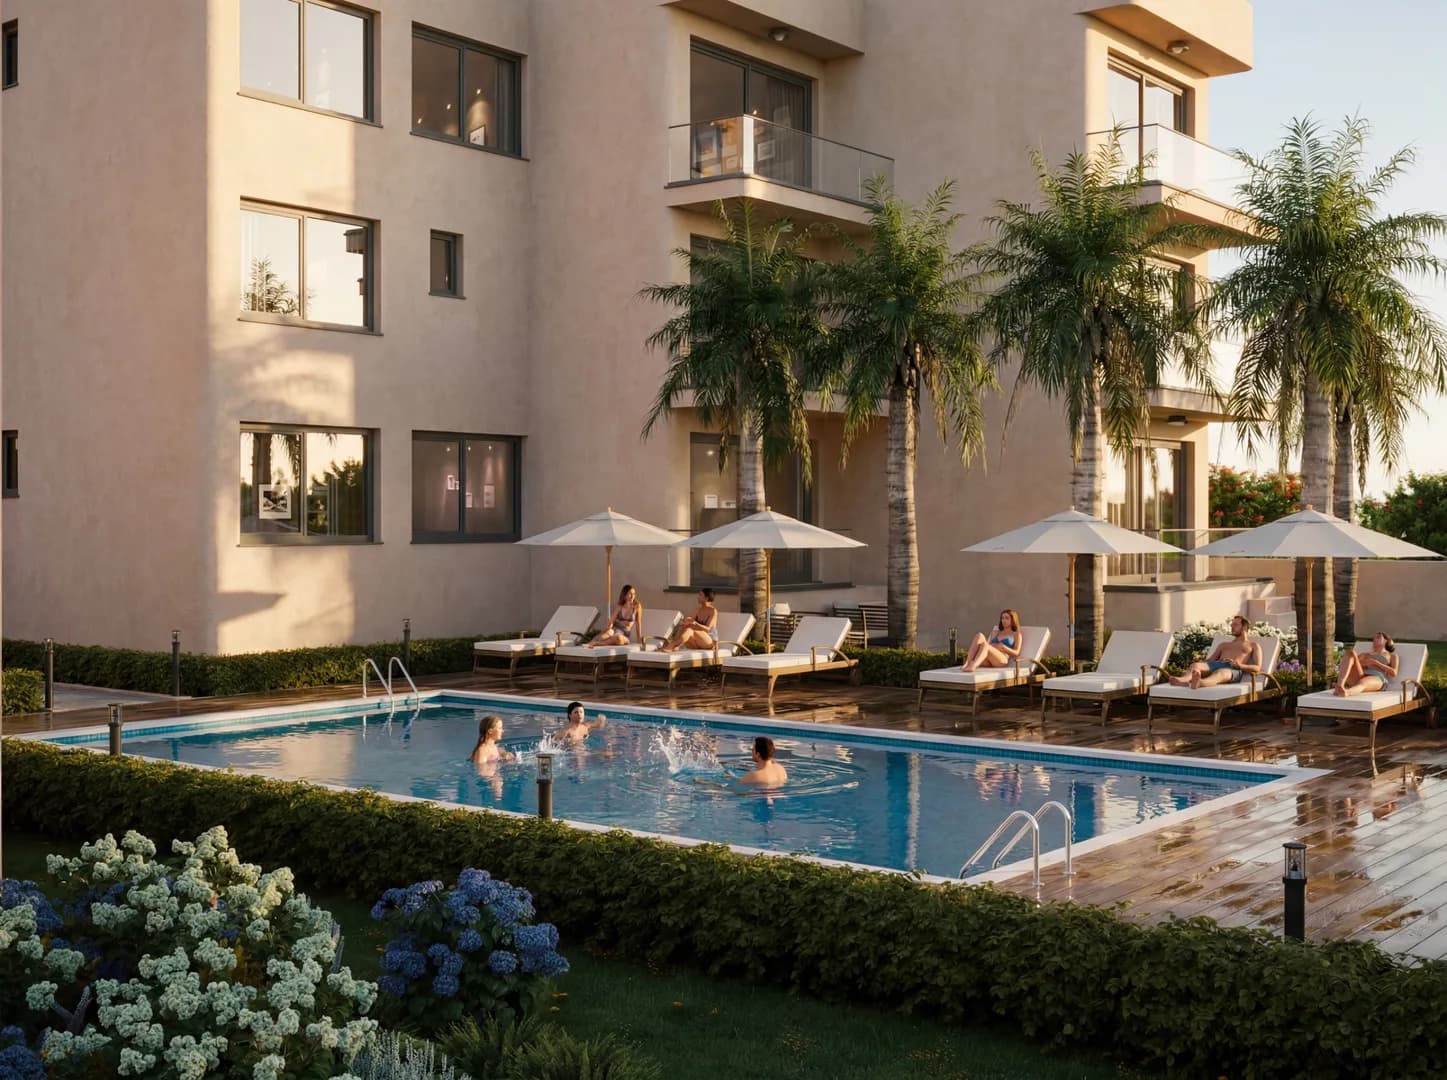
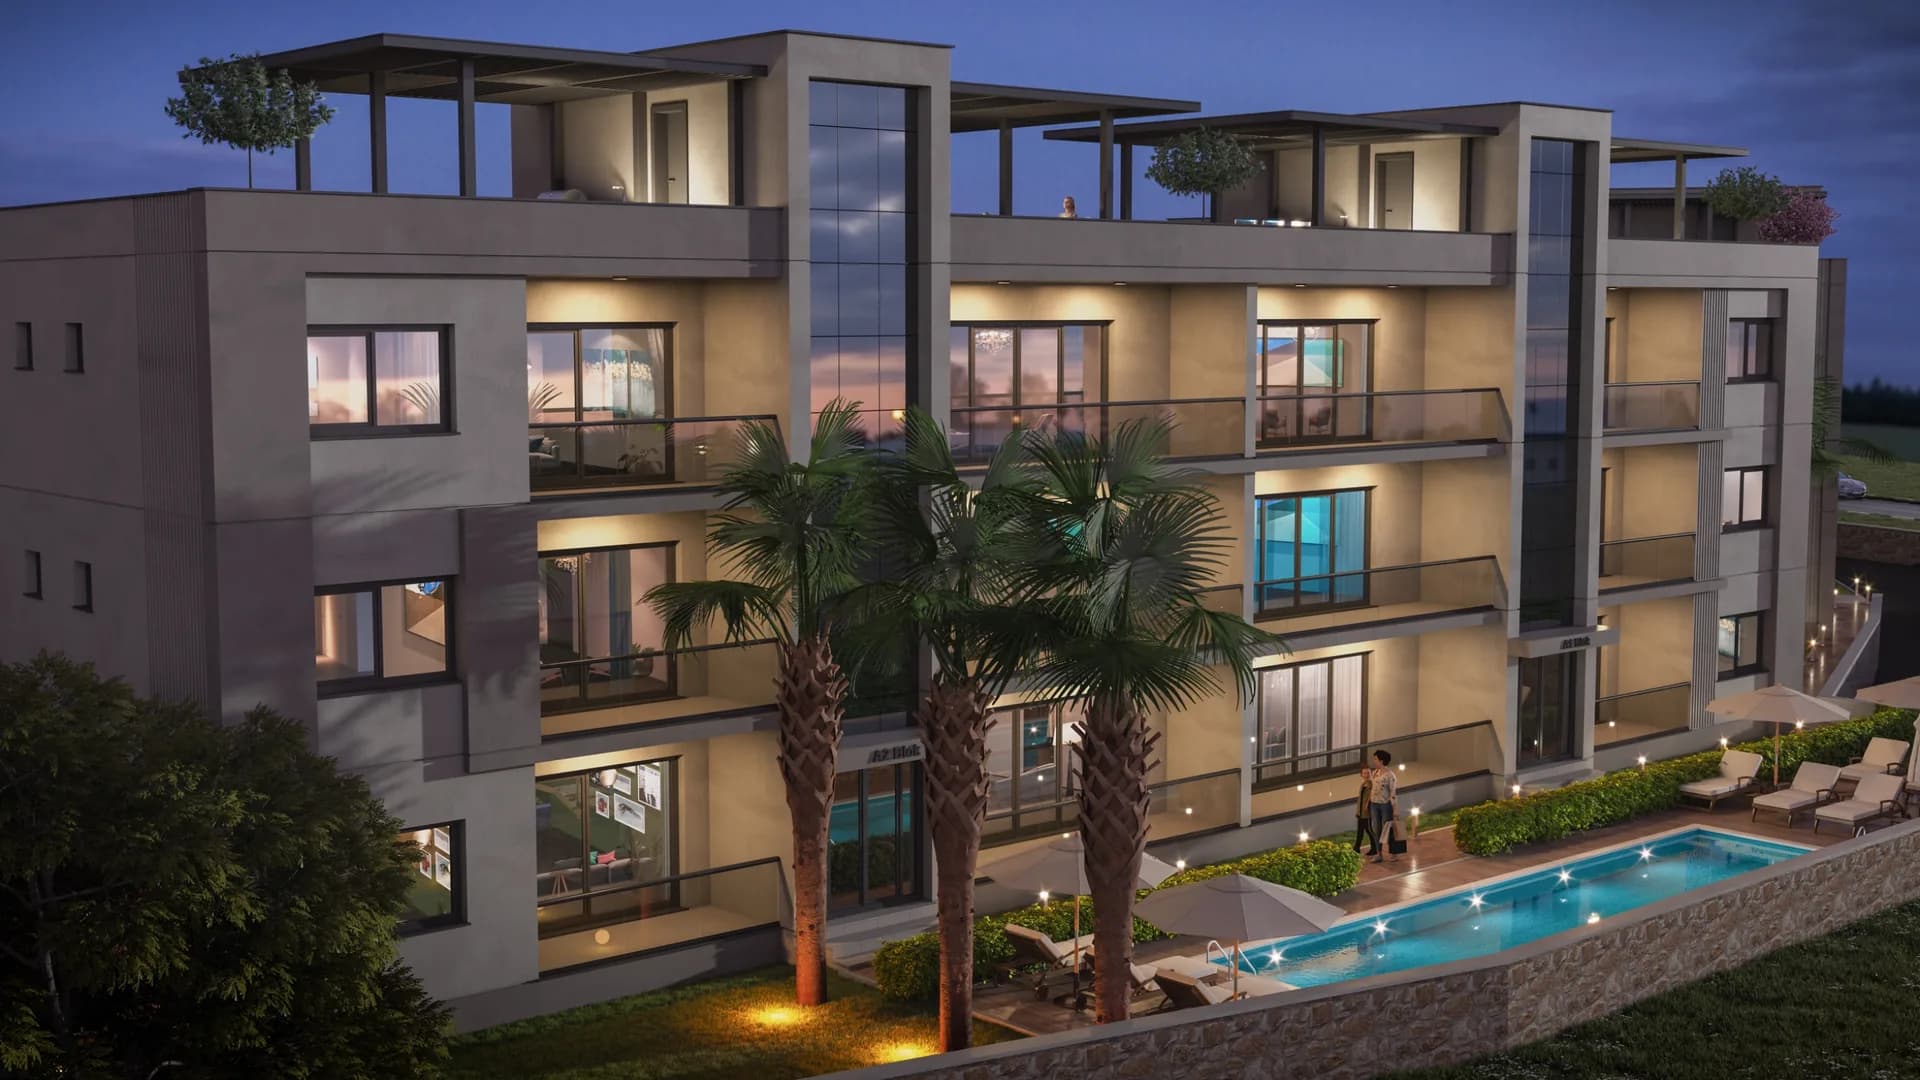
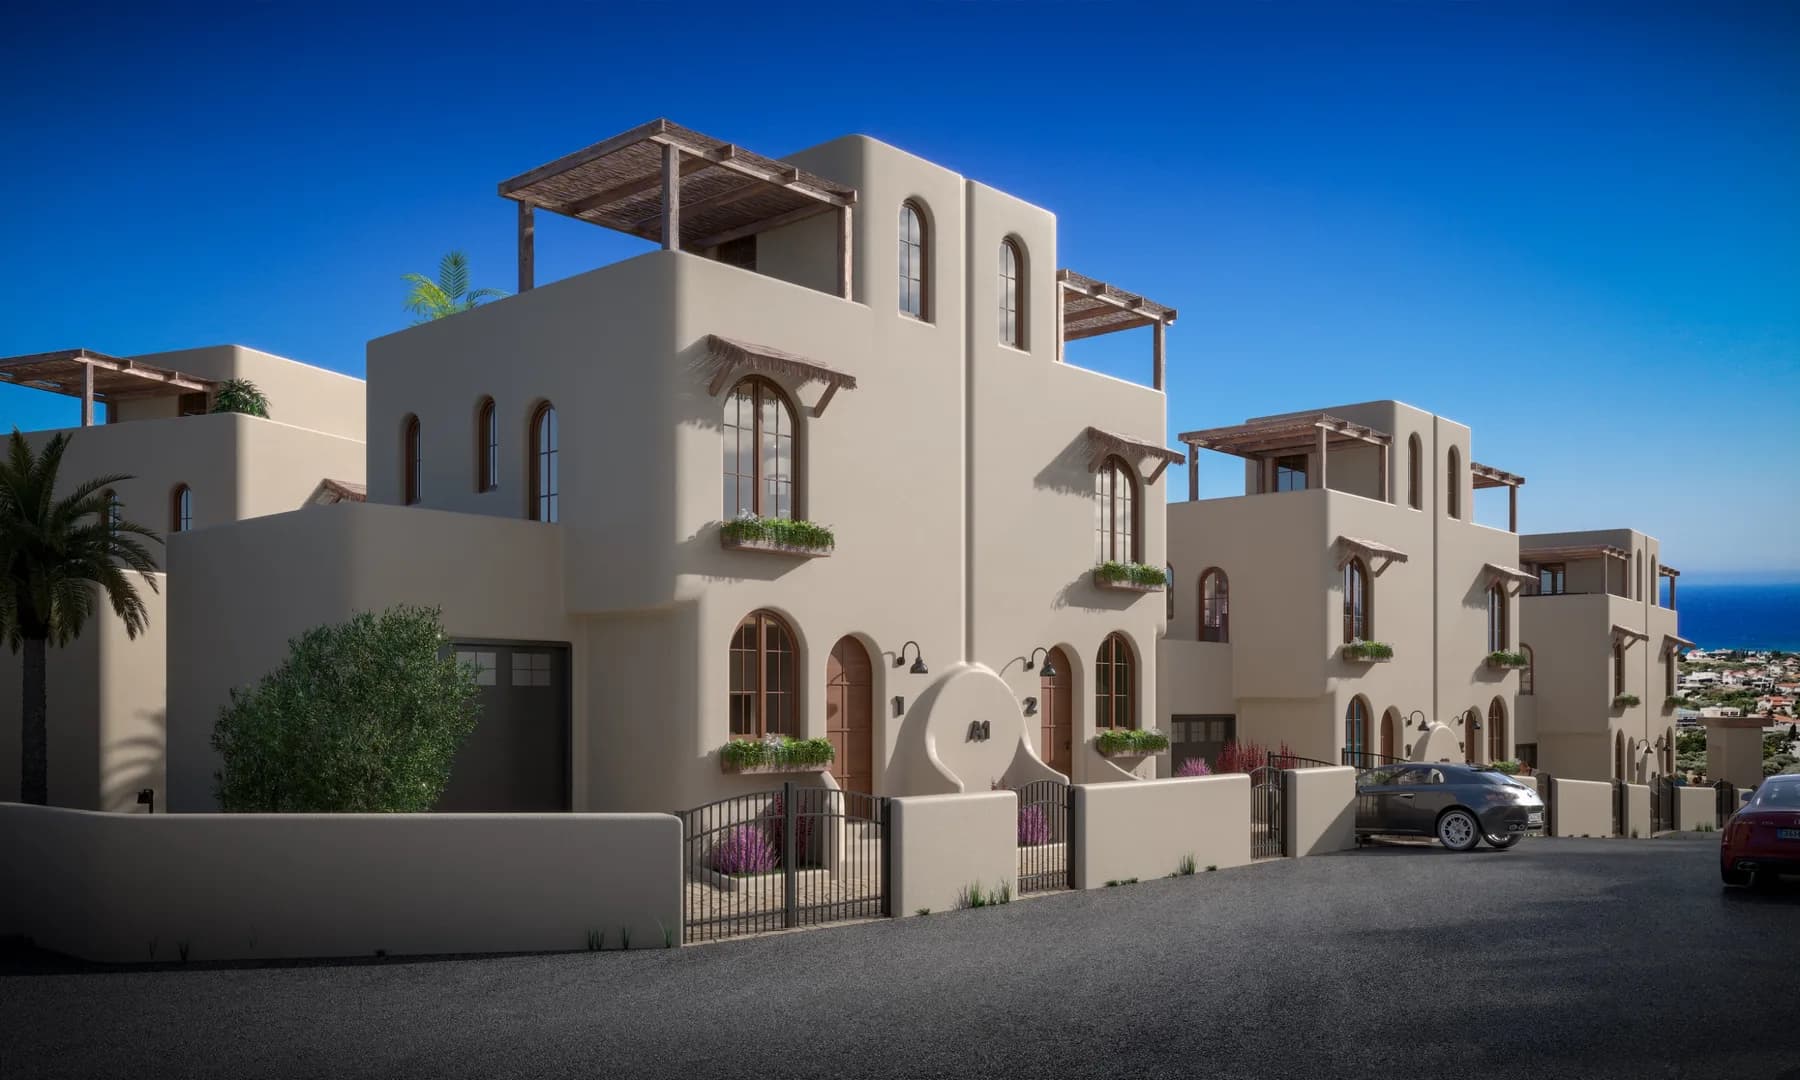
The Belmaris (Lapta) and West Park (Alsancak) project pages show the same plan: a £2,000 deposit holds the unit for 30 days, 35% of the total price is paid when the sales contract is signed, and the remaining 65% is spread over 36 equal monthly instalments. The table applies that plan to the listed price of one unit in each project. The arithmetic is ours.
Item | Belmaris, 2-bed with garden (80 m²) | West Park, 2-bed with terrace (85 m²) |
|---|---|---|
Sale price | £153,000 | £139,000 |
Reservation deposit | £2,000 | £2,000 |
Down payment (35%) | £53,550 | £48,650 |
Balance (65%) | £99,450 | £90,350 |
Monthly instalment (36 months) | about £2,763 | about £2,510 |
Transformer contribution | £1,200 | £1,200 |
Prices taken from the project pages as of November 2026 and subject to change. The pages do not mention interest or any instalment surcharge, and they do not say whether the deposit is deducted from the down payment, so the table shows them separately. Get this settled in the contract.
Because prices differ from unit to unit, it is worth running the same sums for the home you are actually considering. The projects offered with payment plans each list their plan and completion date, and the properties for sale on instalments page puts unit prices and floor areas side by side.
Instalments can run past handover
One detail is easy to miss. Belmaris is due for completion in September 2027 and West Park in April 2027, both with a three-month tolerance period on the project page. A 36-month plan is longer than that. On a contract signed today, part of the instalments will be paid after you get the keys. If you plan to let the apartment and cover some of each instalment with rent, that helps. It also affects when the title deed is transferred, which we come to below.
Sterling and currency risk
Prices and instalments in the TRNC are almost always set in pounds sterling. If you earn in sterling, there is no currency risk at all. If you earn in euros or Turkish lira, the instalment looks fixed but what it costs you changes every month. If sterling rises 10% against your currency, a £2,510 instalment takes 10% more out of your budget, and over 36 months that adds up.
You cannot remove the risk, but you can shrink it: put down a larger deposit to cut the balance, set aside the sterling you need for the schedule in advance, or ask whether the plan can be tied to another currency. Some developers have also announced plans indexed to Turkish lira and local wage growth; if you are offered one, make sure the contract spells out exactly how the index is calculated.
The payment plan and delay clauses in the contract
The payment schedule is the most negotiated part of a North Cyprus contract of sale. Before you sign, make sure these points are in writing:
The amount, currency and due date of each instalment, and which account it is paid into and how.
If you pay late: interest or a penalty, how many missed instalments allow the seller to terminate, and how much of what you paid is refunded on termination.
If the developer is late: the completion date, the tolerance period and the penalty or rent compensation that applies if that is exceeded too.
Early settlement: whether paying off the balance early earns a discount. Our project pages say nothing about an early payment discount, so if one is agreed, put the rate in the contract.
If the land is mortgaged, how your unit will be released from that mortgage before transfer.
Speaking as a contractor, most disputes we see come from terms that were only agreed verbally, not from bad faith. An instalment that was "fine if it's a week or two late" can become a problem once the written clause applies.
Registering the contract and the purchase permit
For a foreign buyer, the stamped contract is registered at the district land registry office and a purchase permit is requested from the Council of Ministers. The decree-law currently in force sets legal deadlines for these steps, and a contract can become void automatically if they are missed. Deadlines change, so ask your lawyer for the current ones. Ownership limits matter at this stage too: Turkish citizens may buy up to 6 apartments or 3 two-storey detached villas per person, other foreign nationals up to 3 apartments or 2 villas, and every purchase needs Council of Ministers permission.
Is the title deed transferred when the last instalment is paid?
In most cases, yes. The same decree-law says that where no mortgage is registered in the seller's favour, the period allowed for the title transfer starts from the date the full price has been paid. The same clause says a developer who fails to transfer the title once nothing is owed must compensate the buyer for the loss caused. The text treats transfers with a mortgage in the seller's favour separately; ask your lawyer whether that route applies to your case.
In practice, the property can stay in the developer's name at the land registry until the final instalment. During that time your protection is the registered contract. The last instalment is not the end of the costs either: taxes and fees are paid on transfer, and how the transfer fee is calculated depends on your nationality and how many properties you already own. The fees also have to be paid within a legal deadline after the permit is published, so add them to the end of your instalment budget now.
Can you buy with a mortgage instead?
Sometimes, but not everyone can. The North Cyprus branches of some Turkish banks offer home loans. For example, Halkbank's TRNC home loan page says the loan is available to TRNC and Turkish citizens resident in the TRNC, for buying a home there, up to 80% of the valuation and for up to 120 months. A first-ranking mortgage is placed on the property, and the sample table on the page is in Turkish lira.
Two things follow. First, we could not confirm a similar bank product for foreign nationals who are not resident in the TRNC, so you will need to ask banks one by one. Second, because the loan needs a mortgage on the property, it has to fit the transfer and permit process; for an off-plan apartment that may mean the loan can only be drawn at transfer. We also found no official source on whether a loan taken out with a bank in Turkey or your home country can be used to buy in North Cyprus, so ask your own bank directly.
If you would like to go through the numbers before you commit, you can talk to our team; we will share the payment schedule, completion date and draft contract in writing.
Frequently Asked Questions
How much is the down payment when buying in instalments in North Cyprus?+
It depends on the project. Belmaris and West Park ask for a £2,000 reservation deposit and 35% of the total price on signing, with the remaining 65% paid over 36 equal monthly instalments (November 2026). Check in the contract whether the deposit is deducted from the down payment.
Do I pay interest on a developer payment plan?+
The plan on our project pages does not mention interest or any surcharge. Terms may differ elsewhere, so compare the total instalment price with the cash price and get it in writing.
Will the title deed be transferred to me before the instalments are finished?+
Usually not. Under the decree-law in force, where no mortgage is registered in the seller's favour, the transfer period starts once the full price has been paid. A transfer with a mortgage in the seller's favour is a separate route; ask your lawyer whether it fits your case.
What happens if I miss an instalment?+
The delay clause in your contract decides: interest or a penalty, a termination right after a set number of missed payments, and the refund due on termination. Read these clauses before signing and get anything unclear settled in writing.
Can foreigners get a mortgage in North Cyprus, or use a loan from their home country?+
Halkbank's TRNC home loan is open to TRNC and Turkish citizens resident in the TRNC. We could not confirm from an official source whether products exist for non-resident foreigners, or whether a loan from a bank abroad can be used to buy here; ask your bank directly.